Skip to content
Anse Accounting Corp.International Tax Center · Seoul Free consultation

For companies entering Korea

Establish your Korean company in about two weeks, fully compliant from day one.

From registration to bookkeeping, tax and payroll, the same two directors handle your Korean entity personally, in English, backed by a tax practice of 254 professionals. Both previously advised clients at PwC Korea. Scope and fees are agreed in writing before any work begins.

  • Response within one business day
  • Microsoft Teams meetings in your time zone
  • Advice in English and Korean

How we can help

Support suited to where your business stands.

Entering Korea

A sound structure and a prompt start.

We recommend the appropriate structure and manage registration with the Korean authorities on your behalf.

  • A clear recommendation: subsidiary, branch or liaison office
  • Registration completed end to end, typically in about two weeks
  • Coordination of capital remittance and bank account opening
  • Bookkeeping, VAT and payroll in place from the outset
Discuss your market entry

Already operating in Korea

A seamless transition from your current adviser.

Where response times or reporting fall short of your head office's expectations, we make the transition straightforward.

  • Prior records obtained from your current adviser on your behalf
  • English-language reporting prepared for head-office use
  • A review of prior filings for errors and unclaimed refunds
  • Responses to your local team within one business day
Discuss a change of adviser

Expatriates and individuals

The Korean tax you owe, and no more.

Clear advice on personal Korean tax, from arrival to departure.

  • An assessment of whether the 19% flat-rate election is advantageous
  • Annual income tax returns and year-end settlement
  • Tax settlement on departure from Korea
  • Capital gains tax on the sale of a Korean residence
Discuss your personal tax

Our firm

Personal attention from senior advisers, supported by one of Korea's leading tax practices.

Your directors handle your matters personally, supported by a tax practice of 254 professionals that has grown alongside its clients for over a decade.

2007Founded in SeoulNearly two decades of continuous practice
254Professionals in our tax practiceOut of 439 across the firm
127KICPAs, 90% with 10+ years' experiencePlus 77 certified tax accountants
3.3×Revenue growth in ten yearsKRW 25.3bn to KRW 84.2bn

Anse Accounting Corp., founded 2007. Figures as of the fiscal year ended 31 March 2026 from the firm's DART business report; growth compares fiscal years ended March 2016 and March 2026.

Our commitments

Six commitments we make to every client.

Senior advisers, personally involved.

The directors you meet at the initial consultation prepare and review your work themselves.

The full resources of the firm.

Where a matter calls for transfer pricing, incentives, audit or property tax expertise, we bring in the appropriate specialists while remaining your single point of contact.

A response within one business day.

Enquiries from your Korean team or head office receive a response within one Korean business day.

Meetings in your time zone.

Microsoft Teams consultations at a time convenient to you, whether in Europe, the Americas or Asia.

Reporting your head office can rely on.

Filings, tax positions and financial statements explained in clear English, with the Korean originals retained on file.

Fees agreed in advance.

Scope, timetable and fees are confirmed in writing before any work begins.

Our advisers

The advisers you meet are the advisers who do the work.

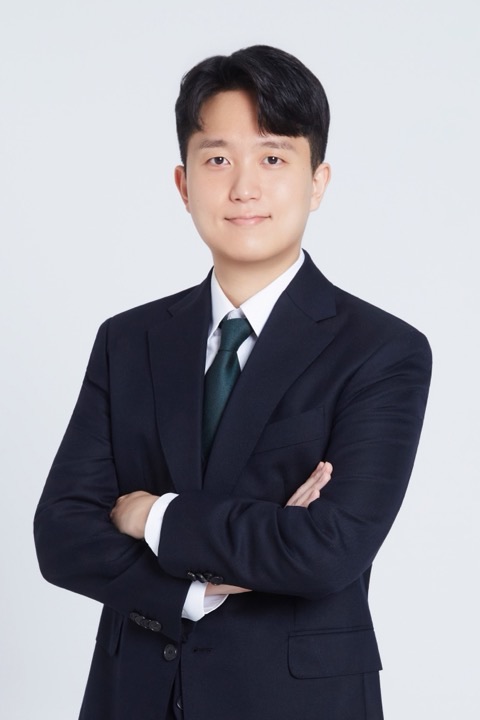
Minsoo Park, KICPA, Director at Anse Accounting Corp.

Minsoo Park, KICPA

Director · Anse Accounting Corp.

  • Formerly PwC Korea, Tax
  • Seoul National University
Profile and articles →
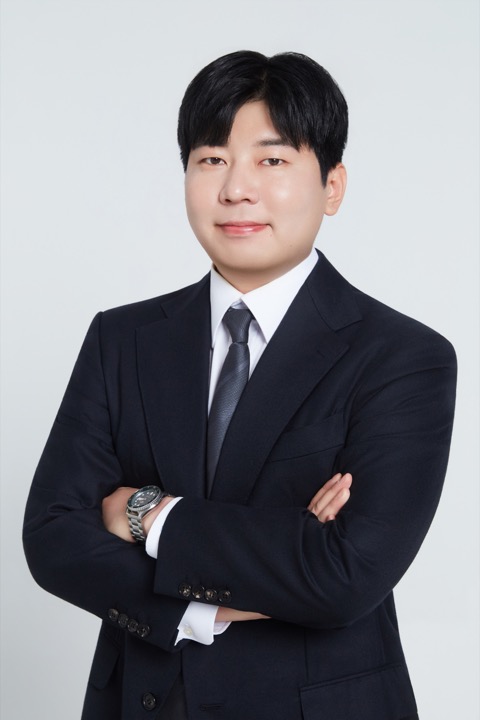
Woosuk Lee, KICPA, Director at Anse Accounting Corp.

Woosuk Lee, KICPA

Director · Anse Accounting Corp.

  • Formerly PwC Korea, Tax and Financial Advisory
  • Yonsei University
Profile and articles →

Depth beyond the engagement team. Where a matter requires additional expertise or capacity, we draw on Anse Accounting Corp.'s tax practice of 254 professionals, including 127 KICPAs, while your director remains your single point of contact.

Getting started

Three steps, beginning with a free consultation.

  1. Initial consultation

    Share your plans with us. We identify the immediate priorities and what can follow later.

    Free of charge, without obligation
  2. Written proposal

    Scope, timetable and fees set out in writing, so the engagement is clear from the outset.

    Before any work begins
  3. Ongoing service

    Registrations, filings and reporting delivered to an agreed calendar, with a named director as your contact.

    Response within one business day

Services

Comprehensive support for your Korean entity.

Market entry and entity setupThe right entity, established promptly and correctly.
  • Subsidiary, branch and liaison-office options compared
  • Foreign investment notification and tax registrations
  • Bank account and foreign-exchange filings coordinated
  • Liaison with Korean authorities, registration specialists and lawyers
Discuss entity setup →
Bookkeeping and financial reportingMonthly accounts and reporting your head office can rely on.
  • Monthly bookkeeping, reconciliations and document review
  • Month-end and year-end closing
  • Financial statements and reporting packs in your group format
  • Coordination with head-office finance and external auditors
Discuss bookkeeping →
Corporate tax, VAT and local taxEvery return filed accurately and on time.
  • Annual and interim corporate income tax returns
  • VAT returns and e-tax invoice reviews
  • Local income tax, registration and resident tax filings
  • Acquisition tax, property tax and comprehensive real estate holding tax
Discuss tax compliance →
Payroll and expatriate income taxAccurate payroll and fair taxation of expatriate staff.
  • Monthly payroll, withholding and year-end settlement
  • Social insurance and retirement pension administration
  • Expatriate returns and 19% flat-rate election reviews
  • Departure settlement and home-sale tax for individuals
Discuss payroll →
Cross-border tax and transfer pricingProtection against double taxation on intra-group payments.
  • Withholding tax on dividends, interest, royalties and service fees
  • Tax treaty relief and permanent establishment reviews
  • Related-party pricing, disclosures, master and local files
  • Advance pricing agreements with your overseas tax team
Discuss cross-border tax →
Tax incentives and government grantsThe credits and grants available to you, fully claimed.
  • Investment and R&D tax credits
  • National strategic and new growth technology incentives
  • Cash grants, customs relief and site support
  • Free Economic Zone and Foreign Investment Zone options
Discuss incentives →
Tax reviews, refunds and audit supportOverpaid tax recovered and audits approached well prepared.
  • Reviews of past filings for errors and omissions
  • Amended returns and tax refund claims
  • Records and responses for tax authority inquiries and audits
  • Tax rulings and appeals within the agreed scope
Discuss a tax review →
Pillar Two assessment and reportingEarly clarity on your Korean global minimum tax position.
  • Group scope and constituent-entity analysis
  • Safe-harbour eligibility and effective tax rate calculations
  • GloBE information and top-up tax returns
  • Coordination with group tax and CbCR teams
Discuss Pillar Two →

Free 30-minute consultation

Arrange a free consultation with a director.

Please share a brief outline of your plans and your availability. We will respond within one Korean business day to confirm a Microsoft Teams meeting.

  • Your current position and the deadlines that matter most
  • The appropriate structure or next step
  • Our proposed approach and how fees would be determined

Consultation request

Fields marked are required.

A brief outline is sufficient. Please do not include tax records, identification or bank details.

Alternatively, open an email draft or write to [email protected].

Frequently asked questions

Before your consultation

Is the initial consultation free of charge?

Yes. The 30-minute consultation is free of charge and carries no obligation. Should you wish to engage us, we will send a written proposal afterwards.

How long does it take to set up a company in Korea?

Typically about two weeks once your head-office documents are ready. Invest KOREA, the government's investment agency, gives the same estimate: investment notification on the day, capital remittance and incorporation in a few days each, and business registration in about a week. Documents that need notarisation or an apostille abroad, and full bank account activation, can add time. We will provide a realistic timetable at the initial consultation. Invest KOREA guide ↗

We already have an adviser in Korea. How does a transition work?

With your authorisation, we obtain the accounting records and filings from your current adviser and assume responsibility from there.

Do two directors have sufficient capacity for our needs?

Yes. Your director leads and reviews your work personally and draws on the firm's tax practice of 254 professionals whenever additional capacity or specialist expertise is required.

Can meetings be held outside Korean business hours?

Yes. Microsoft Teams consultations are scheduled to suit your time zone. Meetings at our Seoul office can also be arranged.

Do you work in English?

We work in English and Korean. Reporting for your head office is prepared in English, and Korean filings and source documents are retained on file.

Korean tax reference

Company setup and tax in Korea: key facts

General information with links to official sources. Key facts checked against those sources on 24 October 2026.

How can a foreign company set up in Korea?

A foreign company usually chooses one of three forms. A local corporation (subsidiary) is a Korean company registered under the Foreign Investment Promotion Act and may carry on any permitted business. A branch office is part of the foreign company and carries on the same business as its head office. A liaison office may not earn revenue and is limited to non-sales activities such as market research and business contacts. Branch and liaison offices are established under the Foreign Exchange Transactions Act.

Source: Invest KOREA, how foreigners can start a business ↗Read the full guide →

What is the minimum investment for a foreign-invested company in Korea?

KRW 100 million. Foreign direct investment under the Foreign Investment Promotion Act generally means an investment of at least KRW 100 million by which a foreign investor holds 10% or more of the voting shares or equity of a Korean company. No minimum investment applies to a branch or liaison office.

Source: Invest KOREA, definition of foreign direct investment ↗Read the full guide →

What is the corporate income tax rate in Korea in 2026?

For fiscal years beginning on or after 1 January 2026, national corporate income tax is charged at 10% on taxable income up to KRW 200 million, 20% above KRW 200 million up to KRW 20 billion, 22% above KRW 20 billion up to KRW 300 billion, and 25% above KRW 300 billion. Corporate local income tax is charged separately at standard rates of 1% to 2.5%.

Source: National Tax Service; Corporate Income Tax Act, Art. 55 ↗Read the full guide →

What tax returns does a Korean company file each year?

A company with a December year-end generally files its corporate income tax return by 31 March, its corporate local income tax return by 30 April, interim corporate income tax by 31 August, and VAT returns by the 25th of January, April, July and October. Payroll withholding tax is generally paid by the 10th of the following month. Dates move for weekends and public holidays.

See the full filing calendar ↓Read the full guide →

What is the 19% flat tax for foreign employees in Korea?

Eligible foreign employees may elect to have their Korean employment income taxed at a flat national rate of 19% instead of the ordinary progressive rates, for up to 20 years from the date they first work in Korea. Local income tax is charged separately. The election requires an application, exclusions apply, and under the current law the first working day must generally fall on or before 31 December 2026.

Source: Restriction of Special Taxation Act, Art. 18-2 ↗Read the full guide →

Does Pillar Two apply in Korea?

Yes. Korea's Income Inclusion Rule applies to fiscal years beginning on or after 1 January 2024, and the Undertaxed Profits Rule from 1 January 2025. The rules generally cover groups with consolidated revenue of at least EUR 750 million in at least two of the four preceding fiscal years. Korea's domestic minimum top-up tax applies from fiscal years beginning on or after 1 January 2026. GloBE returns are due 15 months after the fiscal year-end, or 18 months for the first applicable year, and not before 30 June 2026.

Source: NTS global minimum tax portal ↗Read the full guide →

Rates, Pillar Two and filing deadlines in detail

Last reviewed 8 September 2026. Select a topic for details.

Korean taxes at a glanceCorporate income tax rates, the 19% flat rate for foreign employees and the Pillar Two revenue threshold

Korea / At a glance

Selected Korean Tax Rates

Last reviewed

10–25%

National corporate income tax

Progressive rates of 10%, 20%, 22% and 25% for ordinary for-profit corporations, for fiscal years beginning on or after 1 January 2026. Local income tax is separate.

Source: National Tax Service

19% elective

Foreign employee income tax

Eligible foreign employees may elect the national flat rate for up to 20 years from first work in Korea. Local income tax is separate; the normal first-work deadline is 31 December 2026.

Check the eligibility conditions

The election requires an application and is subject to exclusions, including certain related-party and daily workers. Regional-headquarters and other statutory exceptions may apply. Compare it with ordinary taxation for your circumstances.

Source: Restriction of Special Taxation Act, Art. 18-2

€750million

Pillar Two revenue threshold

Generally, consolidated revenue of at least €750 million in at least two of the four preceding fiscal years. Korean obligations depend on group structure and applicable exclusions.

Source: NTS global minimum tax portal
Pillar Two in KoreaWhen the IIR and UTPR apply, the filing timetable and the 2026 OECD safe harbour update

Pillar Two in Korea

Understand your Korean Pillar Two obligations.

Start with the group structure, consolidated financial statements and CbCR data. We help identify the Korean entities, applicable rules and information needed for a scope assessment.

Request a scope discussion

Last reviewed

Scope & commencement

IIR: FY 2024 · UTPR: FY 2025

Korea’s Income Inclusion Rule applies to fiscal years beginning from 1 January 2024; the Undertaxed Profits Rule follows from 1 January 2025. Check entity status and allocation rules before assuming a payment obligation.

Filing timetable

15 months · 18 in the first year

The standard GloBE filing period is 15 months after year-end, extended to 18 months for the first applicable year. For a first in-scope year ending 31 December 2024, the deadline was 30 June 2026.

Adopted in Korea

Transitional CbCR safe harbour extended

Korea has written the OECD extension into its law: the transitional safe harbour covers fiscal years beginning on or before 31 December 2027 and ending on or before 30 June 2029 (Enforcement Decree of the Adjustment of International Taxes Act, Art. 138, as amended February 2026). The election is made each year, and a jurisdiction that does not qualify in one year cannot use it in later years.

Korean tax filing calendarGeneral deadlines for a December year-end company, from corporate income tax to GloBE returns

Filing calendar

Know what is due. And when.

General deadlines for a corporate taxpayer with a December year-end. Your entity’s requirements, exemptions and extensions need a separate check.

Last reviewed

ObligationGeneral deadlineWhat to check

Corporate income tax

National Tax Service
Due31 March3 months after year-end
Annual corporate return. Available extensions require their own eligibility and procedural review.

Corporate local income tax

Local government
Due30 April4 months after year-end
A separate local return, including allocation between relevant municipalities.

Interim corporate income tax

National Tax Service
Due31 August2 months after the interim period
Generally covers the first six months. Check whether the entity is exempt from interim filing.

VAT

National Tax Service
Due25 January · 25 JulyFinal returns
Corporations generally also file preliminary returns by 25 April and 25 October. Entity-specific exceptions apply.

Payroll withholding

National & local tax authorities
Due10th of the following monthGeneral monthly payment rule
Check approved semiannual payment arrangements and year-end settlement/payment-statement obligations separately.

Property tax

Local government
DueJuly · SeptemberAccording to the tax notice
Generally based on ownership at 1 June. Asset type determines the payment period; comprehensive real estate holding tax is a separate national tax.

International transaction disclosures

National Tax Service
Due30 June6 months after the year-end month
International transaction statement and other documents under Article 16(2), subject to applicable submission and exemption conditions. Article 16 ↗

Master file, local file & CbCR

National Tax Service
Due31 December, following year12 months after the year-end month
Documentation under Article 16(1). Thresholds, responsible reporting entities and notification duties differ by document. Article 16 ↗

GloBE information & top-up tax returns

National Tax Service
Due15 months after year-end18 months for the first applicable year
Example: a first in-scope year ending 31 December 2024 had a 30 June 2026 deadline. Group filing arrangements and Korean requirements must be checked. NTS GloBE portal ↗

These are general statutory deadlines, not a complete entity-specific filing schedule. Weekend and public-holiday adjustments, approved extensions and special rules can change the actual date. National filing guidance: National Tax Service; local filing guidance: Wetax.

Visit us

Our offices in Seoul

Seocho office

5F Wonyoung Building, 106 Myeongdal-ro, Seocho-gu, Seoul, South Korea
서울특별시 서초구 명달로 106, 원영빌딩 5층

Google Maps ↗ · Naver Map ↗

Please arrange a visit in advance.

Head office

1F Anse Building, 41 Yeongdeungpo-ro 84-gil, Yeongdeungpo-gu, Seoul 07355, South Korea

Main line +82 2-829-7575 · Fax +82 2-718-8565

Privacy notice and terms for consultation requests

Updated 9 October 2026.

The form collects your name, email, situation, time zone, preferred times, message and consent, plus company and country if provided, so Anse Accounting Corp.'s International Tax Center can arrange your consultation and respond. It is not a marketing signup.

Submissions are stored in this website's inquiry service and are available to the practice through its internal inbox. A copy is sent by email to the practice mailbox ([email protected]) through our email delivery provider, Resend. Initial request records are automatically removed after 90 days. Records relating to a later engagement are handled under that engagement's terms.

A displayed reference confirms receipt by the inquiry service; it does not confirm that an adviser has read the message. Do not include resident registration numbers, passport copies, bank details, payroll files or other sensitive documents.

Sending a request does not appoint us as your adviser or confirm an engagement, and no fee is agreed through this form. The free consultation provides general guidance; advice on a specific tax position is given only under a written engagement.

To withdraw consent or ask about access, correction or deletion of your details, contact [email protected]. You may decline consent and telephone the office instead; the form cannot be submitted without consent.